


Best Savings Provider 2025 & 2026 | bonkers.ie Awards
Please note, this is an informational page. We do not offer State Savings products at Raisin, but you can compare and open a variety of competitive savings accounts with rates up to 3.65% AER.
Savings Bonds, Savings Certificates, National Solidarity Bonds, and Prize Bonds are all
Returns on fixed-term State Savings and Prize Bonds are tax-free (Deposit Accounts are subject to DIRT)
While the advertised total returns can seem impressive, it's important to , so you can easily compare with other accounts and know how much money you will get back
The information provided here is for informational and educational purposes only and does not constitute financial advice. Please consult with a licensed financial adviser or professional before making any financial decisions. Your financial situation is unique, and the information provided may not be suitable for your specific circumstances. We are not liable for any financial decisions or actions you take based on this information.
Ireland State Savings is the brand name for the range of Government-backed personal savings products offered by the National Treasury Management Agency (NTMA). They’re also referred to as An Post State Savings or Post Office State Savings.
When you invest in an Ireland State Savings product, you’re placing your money directly with the Irish Government. Whether you opt for one of the fixed-term savings products or Prize Bonds, the Government is obliged to repay your investment along with any interest or prize winnings.
Unlike commercial bank deposits capped at €100,000 under the Deposit Guarantee Scheme, Ireland State Savings carry an unlimited statutory guarantee backed by the State.
There are several types of Ireland State Savings products available. Here’s a brief overview of some of the products you can choose from:
A Savings Bond is a three-year fixed rate savings account. You can currently save a minimum of €50 and a maximum of €120,000 per individual, per issue.
Five-year term, usually offering a slightly higher rate. You can invest between €50 and €120,000 per issue (or €240,000 for joint holdings).
Available for 10 years — the longest duration among State Savings products. Same investment limits as above.
Prize Bonds don’t pay interest; instead, your savings enter a weekly prize draw. Prizes range from €100 to €100,000, with a €500,000 prize in the final draw each month.
You can buy in units of €6.25, minimum €25, maximum €250,000. Winnings can be paid to your bank account or reinvested.
Generally speaking, Ireland State Savings and An Post State Savings refer to the same Irish Government-backed savings products.
Ireland State Savings are offered by the NTMA and can be bought directly via the Ireland State Savings website. An Post is responsible for the sale and administration of Ireland State Savings products, which you can open through Irish Post Offices.
Whether you call them State Savings, An Post State Savings, or Post Office State Savings, you’re effectively referring to the same range of savings products.
This depends on the product you choose:
Fixed-term products: You receive your deposit plus interest at the end of the term. You can withdraw early with seven days’ notice, but you will only earn interest accrued up to the most recent completed anniversary date (0% for partial mid-year periods).
Prize Bonds: Redeemable any time after 90 days; repayment may take a few days to reach your account. You’ll get back the amount you paid (plus any prizes, if they were added to your balance).
For a more flexible option, Ireland State Savings also offers a deposit accountwith easy access to your funds. You can withdraw up to €3,000 a day at the Post Office.
As of October 2026, the State Savings rates are as follows:
3-Year Savings Bond | 3 years | 1.96% |
5-Year Savings Certificate | 5 years | 2.29% |
6-Year Instalment Savings | 6 years | 2.33% |
10-Year National Solidarity Bond | 10 years | 2.66% |
Prize Bonds | N/A | 1.50% (Prize Fund rate) |
Deposit Account | N/A | 1.25% (variable) |
Source: https://www.statesavings.ie/our-products
While State Savings offers tax-free returns, rates may still be lower compared to other savings accounts or investments. To assess the true return, it's important to focus on the annual equivalent rate (AER).
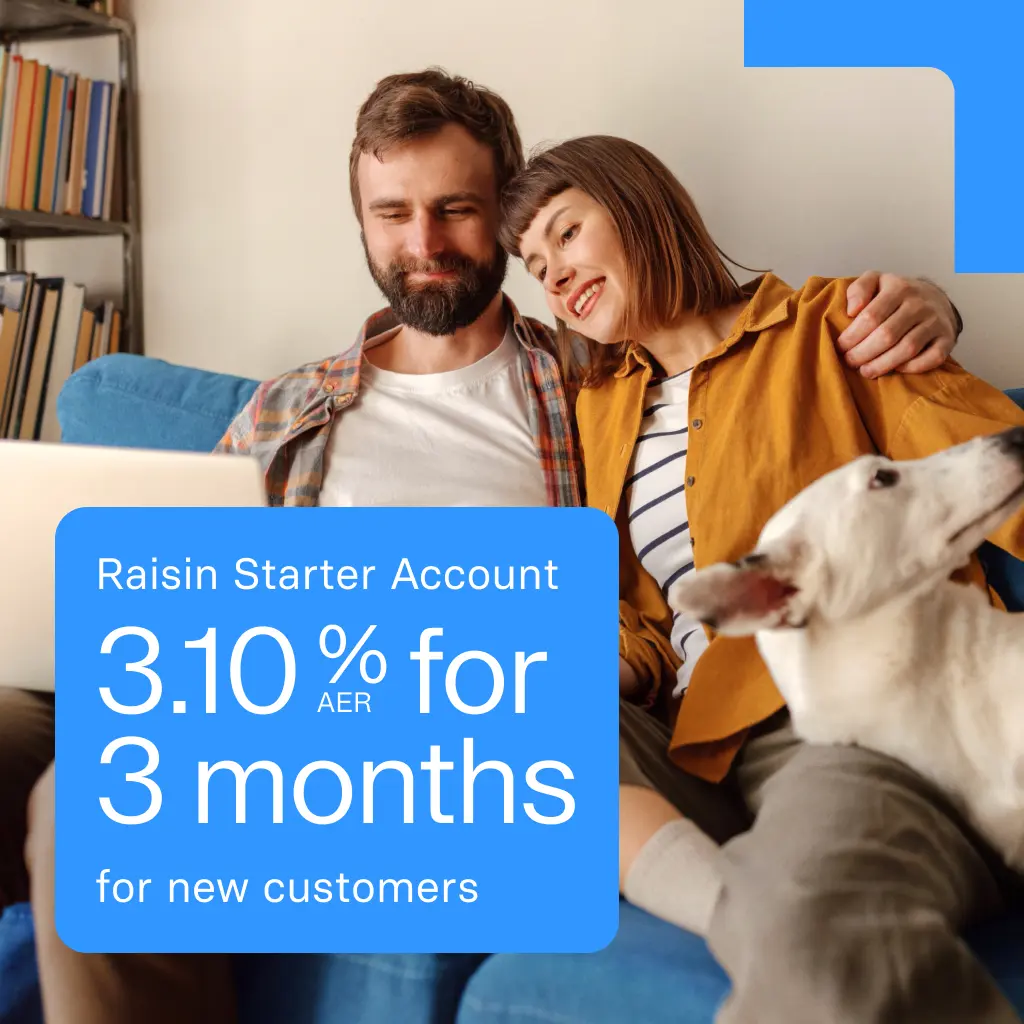
Put your cash to work with a secure, high-yield savings account. Open in minutes, deposit from €1, and earn a fixed 3.10% AER over three months. Enjoy full flexibility to add or withdraw funds at any time, with no fees. At the end of the term, you can seamlessly move your balance to another savings account through Raisin. All deposits are protected up to €100,000 per person, per bank under the German Deposit Guarantee Scheme.
Effective 30 August 2026 for fixed-term products/deposit accounts and 1 September 2026 for Prize Bonds, the National Treasury Management Agency (NTMA) increased rates across several offerings.
The NTMA periodically reviews the State Savings interest rates, but no further updates have been announced.
No. One of the main benefits of Ireland State Savings is that returns are tax-free, though Deposit Account interest is subject to 33% DIRT. Fixed-term or Prize Bond winnings are exempt from deposit interest retention tax (DIRT), which is set at 33% in 2026. Returns are also exempt from income tax, pay related social insurance (PRSI), and capital gains tax in Ireland.
No fees apply for standard lodgements or withdrawals.
For competitive interest rates, some savers look to saving beyond Ireland. At Raisin, you can access high-yield savings accounts through our partner banks across Europe. Raisin’s minimum term for selected fixed term deposits is just one month. Savers can benefit from a fixed interest rate, but with a wide range of saving terms to choose from.
What’s more, deposits of up to €100,000 per person, per bank are protected under the national deposit guarantee scheme of the country where the bank is headquartered.
As always, this depends on your individual circumstances.
Although the tax-free earnings and security that come with Ireland State Savings make them popular among savers, it’s worth comparing the returns against other options.
State Savings products often highlight the ‘total return’ for the full term. For example, the 10-year bond might be advertised as offering a total return of 30%, but that doesn’t mean you’re earning 30% every year. Focusing on the AER (annual equivalent rate) lets you compare different savings products on a like-for-like basis.
For example, let’s say you invest €1,000 in a 10-year bond. At the end of 10 years, you’ll have €1,300 (based on the 30% total return). But remember that growth is slow in the first few years. If you withdraw your money after two years, you’d only earn around €12.50 in interest in total, which works out to an AER of just 0.62%. The longer you leave your money in, the closer you get to the total return rate, and you only reach the full 30% if you leave your cash in until maturity. That’s why the AER is the more telling figure.
This example underscores why you might want to compare a range of products from the wider market to ensure you’re getting a competitive return.
With Raisin, you can apply to open savings accounts across Europe through one secure online platform. Easily spread your money across fixed interest term deposits and flexible demand deposit accounts, and manage everything with one login. Deposits of up to €100,000 per person, per bank are legally protected by the national deposit guarantee scheme of the country where the bank is headquartered.
Register for a free Raisin Account today to get started.

© 2026 Raisin Bank AG, Frankfurt a.M.

All interest rates displayed are Annual Equivalent Rates (AER), unless otherwise explicitly indicated. The AER illustrates what the interest rate would be if interest was paid and compounded once a year. This allows individuals to compare more easily what return they can expect from their savings over time. Raisin Bank, trading as Raisin, is authorised/licensed or registered by BaFin (Bundesanstalt für Finanzdienstleistungsaufsicht) in Germany and is regulated by the Central Bank of Ireland for conduct of business rules.


